US Stocks Slide as May Jobs Surge Locks In Fed Rate Hike by Year-End
US added 172,000 jobs in May, more than doubling forecasts, driving the S&P 500 to its biggest drop of 2026 and pricing in a Fed rate hike by year-end.

The US economy added 172,000 jobs in May, more than double the analyst consensus of 85,000. S&P 500 futures fell 2.6% at the Monday open, Nasdaq 100 contracts dropped 4.8%, and the 10-year Treasury yield climbed to 4.54%. Bond traders fully priced in a Federal Reserve rate hike before the end of 2026.
What Happened
The Bureau of Labor Statistics released the May employment situation on Friday, 5 June. The nonfarm payroll figure of 172,000 exceeded every economist estimate, and the prior two months were revised sharply higher.
Key figures:
- 172,000 jobs added in May, nearly double the consensus of 85,000
- 4.3% unemployment rate, unchanged and in line with expectations
- 0.3% monthly wage growth, 3.4% year-on-year, both in line with forecasts
- March revised to +214,000, April to +179,000, a combined 93,000 more than previously reported
Sector breakdown: leisure and hospitality accounted for 70,000 of the gains. Local government added 55,000, health care 35,000, and manufacturing 7,000.
Why It Matters for Investors
Strong labour data removes the near-term case for Federal Reserve rate cuts and raises the probability of an additional hike before December. The CME FedWatch tool fully priced in one hike by year-end following the release. The US dollar index climbed to 99.25 and gold fell 0.42% as higher yields made cash-yielding assets more competitive.
The repricing is broad-based. Technology and AI stocks led the decline on Monday, with the Nasdaq near-5% futures drop reflecting the sensitivity of long-duration equity valuations to yield moves. A 25-basis-point shift in the discount rate has an outsized effect on companies whose earnings are projected years into the future.
For bond holders, the 10-year Treasury at 4.54% continues a trend that has compressed prices across duration-heavy portfolios since early 2026. Investors tracking total net worth across all asset classes will see these valuations reflected in updated portfolio figures.
What to Watch This Week
The Federal Reserve does not meet until late July. But this week carries significant monetary policy weight. The ECB meets on Thursday, 11 June, with a 25-basis-point hike from 2.00% to 2.25% fully priced in. A coordinated tightening signal from both the Fed and the ECB would extend pressure on rate-sensitive asset classes through the summer months.
The consensus that major central banks had finished their hiking cycles has shifted. Markets are pricing in a tighter path than investors positioned for cuts had expected.
Keep reading
Related trends
10-Year Treasury Yield Hits Highest Level Since 2007 as AI Safety Fears Slam Chip Stocks
The 10-year Treasury yield hit 5.04% on Tuesday as AI safety warnings from Anthropic and OpenAI triggered a chip-stock selloff ahead of the Fed's rate decision.
ECB Raises Rates to 2.50% as Iran War Fuels Euro Zone Inflation
The ECB lifted its deposit rate to 2.50% on September 10, its second hike this cycle, as energy inflation from the Iran conflict pushes prices higher.
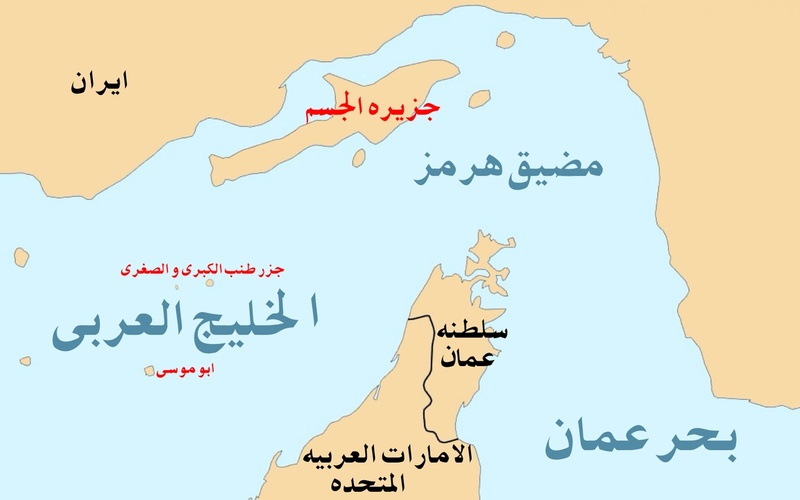
Oil Nears $100 as Iran-Oman Hormuz Deal Nears Final Stage
Brent crude hit $97 as Iran and Oman near a Hormuz shipping deal, reviving inflation fears ahead of Friday's US CPI print and the Fed's next move.
Your complete net worth, finally in one place.
Join investors using Findex to consolidate, track, and grow their portfolios. One view of everything you own.
No payment information required.